When the human in the loop becomes a rubber stamp: what UK regulators found about AI checks
· 5 min read
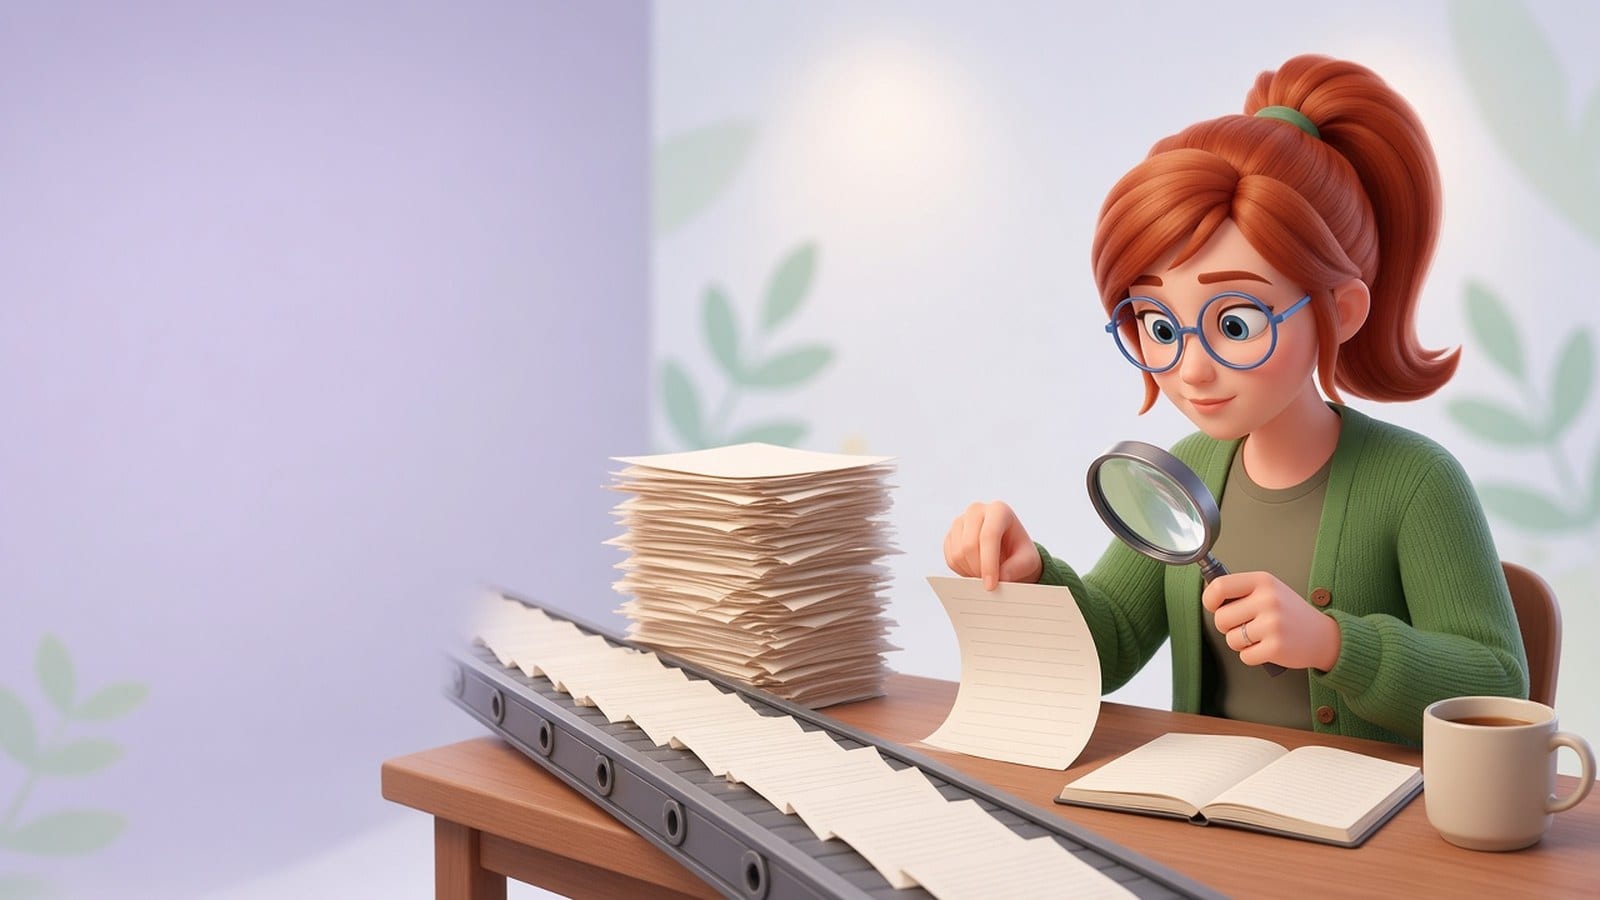
The Bank of England and FCA find most firms approve AI before launch but far fewer keep watching it, and the FCA warns human review can become a tick-box exercise. What leaders should check, and which toolkit tools help.
In brief
Most organisations using AI rely on a simple reassurance: a person checks the output before it matters. New evidence from UK regulators suggests that reassurance deserves a closer look.
The Bank of England and the Financial Conduct Authority surveyed AI use across UK financial services this autumn. Almost every firm reported human approval and review before a system goes live. Far fewer keep watching once it is running. Only around half monitor systems on an ongoing basis, just 39% track the impact on customers, and fewer than half have a plan for handling incidents.
The FCA also describes a firm where the person reviewing AI recommendations slowly stopped challenging them. The checks became a formality, and reviewers accepted recommendations even when there were signs of error.
This article explains what the research found, why the same pattern matters in organisations far beyond banking, and how leaders can tell whether their own human checks still work. It draws on a warning from John Sansbury's The Journey to Service Excellence about governance that exists on paper but not in practice.
It then shows which tools in the AI Enablement Toolkit for Leaders help redesign the human role, from setting out who owns a decision to measuring what a review actually catches. It covers where training for reviewers and senior managers fits, and it is honest about what a management method cannot do on its own, including technical monitoring and regulatory advice.
Somewhere in most organisations using AI, a person is working through a queue of machine-made recommendations, approving each one before it goes out. On the risk register, that person is the control. The uncomfortable question is whether they are still reading.
What the regulators found
On Monday 26 October the Bank of England and the Financial Conduct Authority published their fourth survey of artificial intelligence in UK financial services. It drew 196 responses, with 105 firms completing the full survey.
Adoption is now close to universal among respondents: 86% use AI, and 80% have AI agents deployed. Autonomy is limited. Most agents provide decision support, where the agent recommends and a person decides, and only 2% of respondents have agents with broad autonomy. So in most of these firms, a human really is in the loop.
The more revealing findings are about what happens around that human. More than 90% of full-survey respondents reported human approval, pre-deployment review and vendor due diligence as controls. Ongoing monitoring, leakage testing and periodic review were each reported by only around half. Just 39% monitor customer impact, and fewer than half have incident management and response playbooks. For high-materiality systems supplied by third parties, 81% rely on vendor assurance and contracts, while only 24% say they have deep knowledge of how those systems work.
In other words, the checks cluster at the front door. Once a system is live, firms know far less about how it behaves or what it does to customers.
The human check that stops checking
The FCA's good and poor practice notes on AI, published a week earlier, show what this can look like in practice. They warn against "excessive reliance on human-in-the-loop controls" and describe one firm where the human reviewer role was unclear and "became a tick-box exercise over time". Reviewers increasingly accepted AI recommendations "without sufficient scrutiny" and became less likely to challenge, even where there were signs of errors.
Nobody in that story did anything dramatic. The work arrived faster, the recommendations were usually right, and agreeing became the path of least resistance. The FCA calls the underlying tendency automation bias: placing too much trust in an automated output, even where it may be wrong or incomplete.
The FCA also gives examples of good practice. One firm had reviewers assess affordability cases without seeing the AI's proposed outcome, so it could compare independent human and machine judgements. Others set clear thresholds for when a person must intervene, trained reviewers on a system's purpose and limits, and kept a central inventory of AI agents with named owners.
Why this matters beyond financial services
Banks and insurers are regulated, so they are asked these questions. Most organisations are not, yet nearly every AI programme leans on the same reassurance: a person will check it. If that check has drifted into a signature, the organisation is carrying risk it believes it has removed.
None of this is new. John Sansbury, writing about service management transformation in The Journey to Service Excellence, put it plainly:
"However, do be aware that governance is sometimes little more than a box-ticking exercise."
Applied to AI, Esm reads that as a warning that a control can exist on paper while doing nothing in practice. His book also gives the counterweight, addressed to the people doing the work:
"So as an employee working collaboratively in a team, please don’t be afraid to say, ‘Excuse me, this doesn’t look right.’"
A reviewer who never says that is not reviewing.
Where the AI Enablement Toolkit helps
The AI Enablement Toolkit for Leaders is a leadership method, not software. Several of its tools speak directly to this problem.
- Tool 10, human and AI role design, separates modes such as draft, recommend and act with approval, so the human's job is stated rather than assumed. Its accountability rule is that "The AI did it" describes a mechanism, not an owner. - Tool 11, the ownership and boundaries canvas, records the named owner, approval points, quality checks, escalation route and fallback before a workflow goes live, and when the design will be reviewed. - Tool 16, the minimum governance check, asks whether known failure modes have checks, whether users know how to challenge the output, and whether there is a review trigger after incidents. - Tool 12, the trust-by-design check, includes the pre-mortem prompt "The AI sounded confident while being wrong." - Tool 22, the leader AI enablement dashboard, puts errors, rework and challenge alongside customer outcome, so the measure of a review step is what it catches, not how fast it clears the queue.
Where training fits
The FCA's own description of what reviewers need is close to a training brief: understand the system's purpose and limits, know how to interpret and challenge outputs, manage automation bias, and know when to escalate or override. Senior managers need a different layer, enough understanding of AI risk to challenge it without being technical specialists. That is leadership and reviewer capability, and it is where Esm training and enablement is designed to help.
Honest limits
The toolkit is a management control. It will not monitor a model, detect drift or manage agent credentials; those need technical tools and specialists. It has no agent inventory tool, which the FCA highlights as good practice. It is not legal or regulatory advice, and firms in regulated sectors should check their current obligations rather than recall them. The survey also reflects participating firms, not the whole sector, and the FCA stresses its examples do not create new requirements.
A question to take away
If the people checking your AI stopped reading tomorrow, what in your organisation would tell you, and how long would it take?
Tags: ai-governance, human-in-the-loop, financial-services, leadership, ai-adoption
Sources
- https://www.bankofengland.co.uk/report/2026/artificial-intelligence-in-uk-financial-services-2026
- https://www.fca.org.uk/publications/good-poor-practice/ai-financial-services
Join the Exchange free
Join free to unlock the complete knowledge library.
Founder membership is free for life
More from Esm
10 scheduled AI tasks for service management teams
8 min read
Boards expect AI savings: why almost no organisation is finding them
5 min read
AI rebounding: why some employers are asking back the people AI replaced
5 min read
AI Job Cuts and the Unfilled Role: Where Should Freed Capacity Go?
4 min read
AI and Middle Managers: Who Checks the Work When the Middle Thins?
5 min read
The AI confidence gap: why UK leaders and their teams see different futures
5 min read
Related articles
Boards expect AI savings: why almost no organisation is finding them
Gartner finds 77% of board members expect AI to deliver savings, but only 3% of organisations beat their savings goals through productivity. What leaders should agree instead, and which toolkit tools help.
AI rebounding: why some employers are asking back the people AI replaced
New SHL research finds some UK and US workers replaced by AI were later asked back. Why it happens, and how leaders can understand the work before automating it.
AI Job Cuts and the Unfilled Role: Where Should Freed Capacity Go?
Barclays' AI-assisted job cuts and a quieter freeze on junior hiring raise one leadership question: when AI frees capacity, who decides where it goes before the spreadsheet decides for you?
AI and Middle Managers: Who Checks the Work When the Middle Thins?
New Conference Board research shows managers are being asked to check a flood of AI output just as many organisations expect to need fewer of them. What it means for leaders, and the toolkit tools that help.
The AI confidence gap: why UK leaders and their teams see different futures
New Microsoft research finds 84% of UK leaders are confident about Britain's AI future but only 41% of employees agree. Here is what that gap means for leaders, and four practical ways to close it.
Members
You Cannot AI What You Cannot See
Every university leader is under pressure to show what artificial intelligence will do for the institution. Here is an uncomfortable truth that a recent value stream mapping workshop surfaced, and it has nothing to do with the cleverness…